Flip Chip Packaging is entering 2026 with stronger demand from artificial intelligence, automotive electronics, 5G infrastructure, and advanced consumer devices. Its direct interconnection path supports shorter electrical distances, improved signal performance, and higher packaging density. These advantages matter when processors generate more heat inside smaller systems. The market is growing, but supplier selection is becoming less straightforward.
This guide examines leading Flip Chip Packaging suppliers through manufacturing capability, substrate access, bumping technology, thermal design, quality systems, and delivery consistency. It considers established semiconductor packaging companies, specialized assembly providers, and regional manufacturers with expanding capacity. A credible supplier should demonstrate controlled wafer handling, reliable underfill processes, and stable inspection results. Certifications and public customer evidence also deserve careful review.
The 2026 landscape will likely emphasize hybrid bonding, finer-pitch interconnects, chiplet integration, panel-level packaging, and improved thermal materials. These developments may reduce package size while increasing production complexity. Cost remains important, yet the lowest quotation can hide yield risks, qualification delays, or limited engineering support. The analysis therefore avoids treating market visibility as proof of technical leadership. No list is permanent. Supplier rankings can change with new fabs, acquisitions, regional incentives, and customer qualification results. Some industry forecasts also rely on incomplete disclosures, so readers should verify capacity claims directly. The most useful comparison connects laboratory performance with factory discipline, field reliability, and transparent communication. Small gaps matter. This perspective helps engineers, procurement teams, and investors identify partners that can support demanding designs without overstating their capabilities.
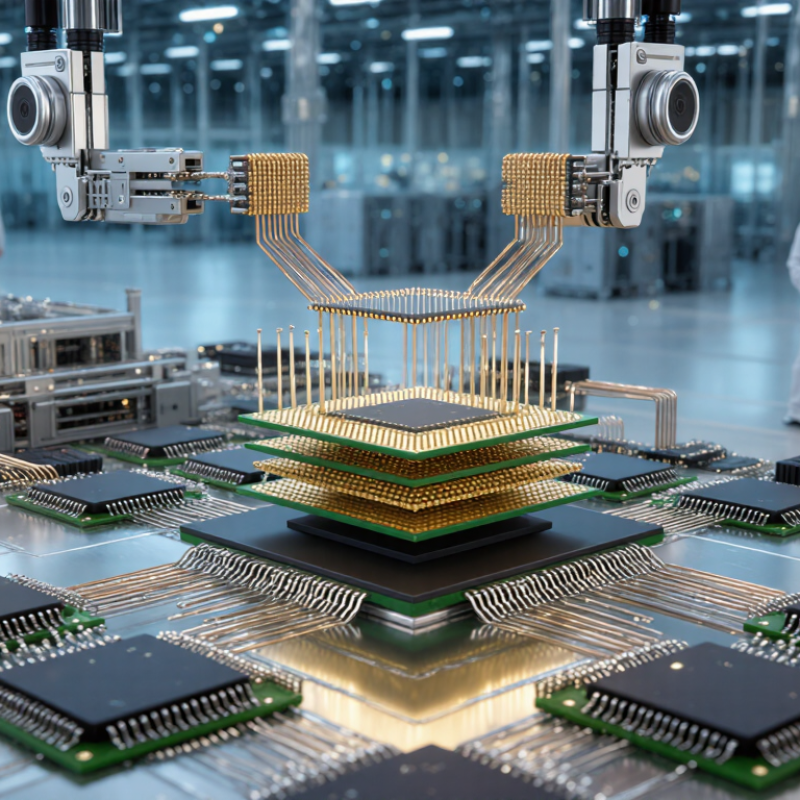
Flip-chip packaging starts with a direct electrical connection. Tiny solder or copper bumps face the die toward the substrate. C4 bumps remain common for robust power and signal paths. Their spacing, height, and collapse profile must match the pad design. In package reviews, I look for voids, nonuniform joints, and warpage after reflow. Small shifts matter. A clean cross-section often reveals more than a glossy specification sheet. Thermal cycling can expose weaknesses that initial electrical tests miss.
Redistribution layers route dense die pads toward wider package connections. Fine-line RDL can reduce substrate complexity and support compact fan-out structures. It also adds process sensitivity. Line width, dielectric thickness, and via shape affect yield. Moisture control deserves attention. So does copper stress. A design may simulate well yet fail after repeated heating. That gap is uncomfortable, but real. Supplier comparisons should include defect data, inspection methods, and traceability, not only cost or advertised density. Independent sampling strengthens confidence.
In 2.5D integration, multiple dies sit beside each other on an interposer. High-bandwidth links become practical, but routing and thermal paths grow difficult. 3D stacking shortens connections further through vertical interconnects. Heat has fewer escape routes. Power delivery becomes a shared problem. Current trends favor hybrid bonding, finer pitches, and stronger thermal management. Yet finer is not automatically better. Assembly tolerance, repairability, test access, and long-term reliability can suffer. I would question any roadmap lacking measured data from thermal, mechanical, and electrical testing. Some assumptions will be wrong. That is why process learning should continue after qualification.
AI accelerators and HBM3E 12-high memory stacks will reshape flip chip packaging demand in 2026. Higher memory density reduces data movement and supports faster model training. However, taller stacks create tighter thermal and mechanical limits. Package suppliers must control warpage, bonding accuracy, underfill flow, and heat removal. Small defects can reduce yield across an expensive stack.
The strongest suppliers will offer more than assembly capacity. They will provide stable process windows, failure analysis, traceable materials, and reliable production data. Engineers should inspect void rates, bump alignment, thermal cycling results, and high-volume yield records. Cooling design also matters. A powerful package can still underperform if heat spreads unevenly across the interposer. This risk is easy to underestimate.
Tips: Compare suppliers using measured evidence, not presentation slides. Request sample cross-sections and process capability data. Check how each supplier handles thin wafers, fine-pitch connections, and rework limits. Ask for thermal test conditions, because results can change with airflow and workload. Do not assume 12-high designs always deliver better value. They may increase capacity, but they also raise inspection, cooling, and yield costs. More refinement is still needed.
| Supplier Segment | Primary Capability | Relevant Technical Dimension | Verified Reference Point | 2026 Demand Signal | Packaging Trend | Qualification Priority |
|---|---|---|---|---|---|---|
| Advanced Packaging Foundries | 2.5D interposer integration, chiplet assembly, silicon bridge integration, and high-density flip chip placement | Logic die-to-HBM proximity and high-bandwidth die-to-die routing | 2.5D packaging places multiple dies on a common interposer or bridging structure, reducing off-package communication distance | Very High | Greater use of chiplet-based architectures and larger integrated package footprints | Interconnect yield, warpage control, thermal performance, and package-level test coverage |
| Outsourced Semiconductor Assembly and Test Providers | Flip chip assembly, underfill, molding, singulation, burn-in, and final test | High-volume manufacturing of large, high-pin-count packages | Flip chip assembly uses solder bumps or copper pillars to connect the die directly to the package substrate | High | Expansion from conventional flip chip toward 2.5D, fan-out, and heterogeneous integration | Throughput, known-good-die handling, process traceability, and advanced test capacity |
| Organic Package Substrate Suppliers | High-density multilayer substrates for processor, accelerator, and memory-integrated packages | Fine-line routing, buildup layers, core thickness, and substrate warpage | Large AI packages require substantially more routing layers and larger substrate formats than conventional mobile packages | Very High | Demand is shifting toward larger panels, higher layer counts, and tighter line-spacing capability | ABF material availability, dimensional stability, electrical loss, and panel-level yield |
| Silicon Interposer Suppliers | High-density redistribution between compute dies and stacked high-bandwidth memory | Interposer area, micro-bump density, passive routing, and electrical loss | Silicon interposers support much denser die-to-die wiring than conventional organic substrates | Very High | Growth in interposer size and routing density for AI accelerators and networking processors | Interposer yield, micro-bump alignment, crack resistance, and supply scalability |
| HBM Stack Assembly Providers | Vertical memory-die stacking, TSV processing, bonding, molding, and stack testing | HBM3E 12-high stack height, thermal path, and stack yield | 12-high HBM3E stacks commonly provide 36 GB per stack, based on twelve 24 Gb memory dies | Very High | Higher stack heights and increased memory capacity per package | TSV yield, die-to-die bonding, thermal uniformity, and stack-level reliability |
| HBM Integration and Package Test Providers | HBM-to-interposer assembly, memory interface verification, thermal screening, and system-level test | Bandwidth, power delivery, signal integrity, and memory error screening | HBM3E is specified at more than 1.2 TB/s peak bandwidth per stack in commonly deployed configurations | Very High | More HBM stacks per accelerator package and greater emphasis on end-to-end memory bandwidth | High-speed test, thermal cycling, repair analysis, and package-level yield correlation |
| Bump and Wafer-Level Processing Providers | Wafer bumping, copper pillar formation, redistribution layers, and wafer thinning | Micro-bump pitch, bump coplanarity, wafer thickness, and alignment accuracy | Fine-pitch interconnects enable shorter electrical paths but increase sensitivity to contamination, warpage, and alignment error | High | Movement toward finer-pitch interconnects and improved wafer-level process control | Coplanarity, defect inspection, electrical continuity, and low-k-die protection |
| Thermal Materials and Assembly Providers | Underfill, mold compounds, thermal interface materials, heat spreaders, and cooling assemblies | Thermal resistance, coefficient of thermal expansion, heat flux, and mechanical stress | Higher HBM stack counts and AI accelerator power density increase the need for improved thermal paths and package-level cooling | Very High | Greater adoption of advanced thermal interface materials, liquid cooling, and co-designed package heat spreading | Thermal cycling, pump-out resistance, void control, and compatibility with fine-pitch structures |
| Inspection and Metrology Providers | Advanced optical inspection, X-ray inspection, warpage measurement, and defect analytics | Micro-bump voids, TSV defects, die shift, package warpage, and substrate defects | Heterogeneous packages require inspection at wafer, die, interposer, substrate, and final-package stages | High | More inline inspection and data-based process control for complex multi-die packages | Detection sensitivity, inspection speed, recipe portability, and manufacturing data integration |
| Advanced Package Design and Test Services | Package co-design, signal-integrity simulation, power-integrity analysis, thermal modeling, and system test | Chiplet connectivity, power delivery, high-speed signaling, and package-level reliability | AI packages combine compute, memory, networking, and power-delivery requirements in a single integrated assembly | Very High | Co-optimization of die, interposer, substrate, cooling, and test rather than package design in isolation | Design-for-manufacturing, multi-die validation, reliability modeling, and test escape reduction |
| Hybrid Bonding and 3D Integration Providers | Wafer-to-wafer and die-to-wafer bonding for high-density vertical integration | Bond alignment, surface preparation, bond strength, and ultra-fine vertical interconnects | Hybrid bonding can remove conventional solder-bump limitations by forming direct dielectric and metal-to-metal bonds | Emerging / Strategic | Increasing research and pilot production for 3D logic, memory, and chiplet integration | Bond yield, surface cleanliness, thermal budget, repairability, and high-volume scalability |
The 2026 flip chip packaging market is being shaped by six leading supplier groups. They include advanced foundries, global assembly specialists, integrated device manufacturers, memory producers, and large Asian packaging providers. Each brings a different advantage, from wafer-level integration to high-volume testing.
Demand is moving toward 2.5D interposers, 3D stacking, and high-bandwidth memory integration. Copper pillar bumps support shorter electrical paths and better signal control. In production lines, engineers watch warpage, voids, and underfill flow closely. A small alignment error can reduce yield across thousands of units. Thermal design is equally important, especially for artificial intelligence accelerators operating inside dense server racks.
Supplier selection now depends on more than price. Buyers examine package reliability, regional capacity, substrate access, and failure-analysis capability. Several leading providers are expanding chiplet platforms and panel-level processes. However, scaling remains uneven. Some solutions look efficient in demonstrations but lose consistency during mass production. That gap deserves more honest reporting. Practical evaluations should include thermal cycling, drop tests, long operating hours, and field-return data. The strongest 2026 partners will combine advanced equipment with disciplined process control, transparent quality records, and engineers who can solve defects quickly.
Global semiconductor market revenue is used as a demand proxy for advanced packaging investment. Growth is being supported by artificial intelligence, high-performance computing, high-bandwidth memory, chiplets, and heterogeneous integration.
Figures are global semiconductor market estimates and forecasts in billions of U.S. dollars. Source: World Semiconductor Trade Statistics, Spring 2025 forecast. The figures represent the broader semiconductor market rather than packaging revenue alone.
Flip chip packaging is moving toward 40–55 µm bump pitch for high-density compute and networking devices. This range leaves little room for placement error. A few microns can reduce solder joint reliability or disturb electrical performance. Qualified suppliers now need stable wafer bumping, fine-pitch assembly, and repeatable inspection data. Production teams commonly review bump height variation, void levels, warpage, and thermal cycling results.
The shift toward 2.5D interposer scaling adds another layer of difficulty. Larger interposers support more chiplets, but they also increase stress during bonding and thermal changes. Engineers must control die placement, underfill flow, and substrate flatness across the full package. X-ray inspection and cross-section analysis remain practical tools, not optional paperwork. Thermal simulation helps, although real production behavior can still differ from laboratory models.
The 40 µm target is attractive. It is not automatically better. Smaller bumps may improve density while narrowing the process window. Some suppliers may report impressive pitch capability but provide limited yield evidence. That gap deserves careful questioning. A reliable evaluation should compare pilot-line results, long-term reliability data, and corrective-action speed. Interposer scaling also requires stronger coordination between design, materials, assembly, and test teams. In practice, one weak interface can undermine an otherwise advanced package.
Hybrid bonding is moving from laboratory demonstrations toward high-volume packaging. The 2024 Yole Group advanced packaging report estimates the market could approach 80 billion US dollars by 2029, supported by chiplet and memory integration. The figure is a forecast, not a guarantee. Real demand will depend on customer qualification and usable yield.
COPPER-TO-COPPER BONDING removes much of the solder-bump height. That enables shorter electrical paths and denser connections. However, surfaces must remain extremely flat and clean. A few particles can create open circuits across an entire wafer. Recent imec research shows sub-micron alignment is technically achievable, but factory repeatability remains the harder problem. Yield remains unforgiving.
Thermal limits are becoming equally important. The International Roadmap for Devices and Systems links advanced integration with rising interconnect and cooling challenges. Meanwhile, the Uptime Institute’s 2024 data-center research reports that high-density computing racks can exceed 100 kilowatts. Packaging suppliers must therefore improve heat spreading, warpage control, and inspection together. Capacity is also tightening: SEMI forecasts semiconductor manufacturing equipment sales of about 121 billion US dollars in 2026. That investment will not automatically create advanced packaging capacity. Engineers still need qualified materials, stable process windows, and enough trained operators. The uncomfortable truth is simple: a faster package can still lose money when its yield is inconsistent.
1 Hayotsrim Street
Nahariya 22311
Israel
Phone: +972 (0)4 9855 121/ 111/ 176
Fax: +972 (0)4 9855 175
Email: sale@dialoguetoolkit.com
Url: www.egmo.co.il
1 Hayotsrim Street
Nahariya 22311
Israel
Phone: +972 (0)4 9855 121/ 111/ 176
Fax: +972 (0)4 9855 175
Email: sale@dialoguetoolkit.com
Url: www.egmo.co.il
An der Autobahn 15
D-28876 Oyten
Germany
Phone: +49 4207 699 40
Fax: +49 4207 6994 40
E-mail: sale@dialoguetoolkit.com
Url: www.hy-lok.de
Distributor in Belgium
Avenue Lavoisier 18B
1300 Wavre
Belgium
Phone: +32(0)471 93 43 12
Email: sale@dialoguetoolkit.com
Url: www.cameco-tubings.be
Distributor in Belgium Flanders
Steenspil 8
4661 TZ Halsteren
The Netherlands
Phone: +31(0)85 0074200
E-mail: sale@dialoguetoolkit.com
Url: www.bergen-ip.eu
Sklarska 70
435 42Litvinov
Czech Republic
Phone: +420 602 110 208
Email: sale@dialoguetoolkit.com
Url: www.hacomost.cz
Rusthollarinkatu 8
Espoo FIN-02270
Finland
Phone: +358 (0) 106137100
Fax: +358 (0) 106137701
Email: sale@dialoguetoolkit.com
Url: www.avs-yhtiot.fi
ZI du Val d’Argent
11 rue Guy Moquet
95100 Argenteuil
France
Phone: +33 1 30 25 94 20
Fax: +33 1 30 25 94 59
Email: sale@dialoguetoolkit.com
Url: defa-inox.fr
An der Autobahn 15
Oyten D-28876
Germany
Phone: +49 – 4207 – 69 94 – 0
Fax: +49 – 4207 – 69 94 – 40
Email: sale@dialoguetoolkit.com
Url: www.hy-lok.de
Skouze 14
Piraeus 18536
Greece
Phone: +30 (0)210-4530240
Email: sale@dialoguetoolkit.com
Url: www.agv.gr
Via Novara 10 / B-C
20013 Magenta
Milano
Italy
Phone: +39 02 97298663
Fax: +39 02 97291855
Email: sale@dialoguetoolkit.com
Url: www.indra.it
Distributor for Lithuania, Estonia & Latvia
Serveces g. 2-27
02121 Vilnius
Lithuania
Phone: +370 (5) 210 22 74
Fax: 370 (5) 210 22 75
Email: sale@dialoguetoolkit.com
Url: tekknow.lt
Distributor for Israel, Moldova, Kosovo, Iceland, Hungary, Slovenia, Romania, Bulgaria & Malta
Buitenvaart 1411
Hoogeveen 7905 SJ
The Netherlands
Phone: +31(0)528 234 084
Fax: +31(0)528 234 084
Email: sale@dialoguetoolkit.com
Url: www.www.dialoguetoolkit.com
Bijsterhuizen 2152
6604 LG Wijchen
the Netherlands
Phone: +31 (0)24 648 93 80
E-mail: sale@dialoguetoolkit.com
Url: www.pdgastechnology.nl
Steenspil 8
4661 TZ Halsteren
The Netherlands
Phone: +31(0)85 0074200
E-mail: sale@dialoguetoolkit.com
Url: www.bergen-ip.eu
Energieweg 14
4691SG Tholen
The Netherlands
Phone: +31(0)85 0074200
E-mail: sale@dialoguetoolkit.com
Url: www.bergen-ip.eu
Strandgata 15A
4307 Sandnes
Phone: +47 91135785
Email: sale@dialoguetoolkit.com
Url: hydraserv.no
ul. Zalogowa 17
Gdansk 80-557
Poland
Phone: +48 58 522 03 80, -81
Fax: +48 58 342 20 10
Email: sale@dialoguetoolkit.com
Url: www.verdigroup.pl
Estrada Nacional 10
Centro Empresarial SADO
Internacional Armazem C 19
2910-809 Setúbal
Portugal
Phone: +351 919 582643
Email: sale@dialoguetoolkit.com
Url: www.arcamo.com
Distributor for Serbia, Croatia, Bosnia & Herzegovina, Montenegro, North Macedonia & Albania
Cara Dusana 205A
11080 Belgrade
Serbia
Phone: +381 60 46 56 086
Email: sale@dialoguetoolkit.com
Url: www.timfluid.com
Partizánska Ľupča 552
032 15 Partizánska Ľupča
Slovak Republic
Phone: +421 903 735 360
Email: sale@dialoguetoolkit.com
Url: www.ecmsystems.sk
C/ Sebastián Elcano 32, 2ª Planta, Puerta 33
28012 Madrid
Spain
Phone: +34 916 794 286
Fax: +34 916 794 287
Email: sale@dialoguetoolkit.com
Url: www.arcamo.com
Distributor for Sweden, Denmark & Faroe Islands
Metalgangen 13
2690 Karlslunde
Denmark
Phone: +45 7384 1230
Fax: +45 7384 1280
Email: sale@dialoguetoolkit.com
Url: pgflowteknik.dk
Distributor for Sweden, Denmark & Faroe Islands
Metalgangen 13
2690 Karlslunde
Denmark
Phone: +45 7384 1230
Fax: +45 7384 1280
Email: sale@dialoguetoolkit.com
Url: pgflowteknik.dk
An der Autobahn 15
D-28876 Oyten
Germany
Phone: +49 4207 699 40
Fax: +49 4207 6994 40
E-mail: sale@dialoguetoolkit.com
Url: www.hy-lok.de
Neumo Mühendislik ve Paslanmaz Çelik San. Tic. Ltd. Şti.
Birlik sanayi Sitesi 6. Cadde No:19
34520 Beylikdüzü/Istanbul
Turkey
Phone: +90 (212) 875 01 41
Fax: +90 (212) 875 23 13
Email: sale@dialoguetoolkit.com
Url: www.neumo.com.tr/
Kirkhill Place
Kirkhill Industrial Estate
Dyce AB21 0GU
United Kingdom
Phone: +44 (0) 1224 775277
Fax: +44 (0) 1224 775040
Email: sale@dialoguetoolkit.com
Url: www.hylokuk.com
ST. Semenovskaya B., D49, APT/FLOOR/OFFICE I/5/16
107023 MOSCOW
RUSSIA
Phone: +7 495 517 7261
Fax: +7 495 360 8062
Email: sale@dialoguetoolkit.com
Url: www.fluid-line.ru